GE Aerospace Beats Again. Why the Stock Won't Follow
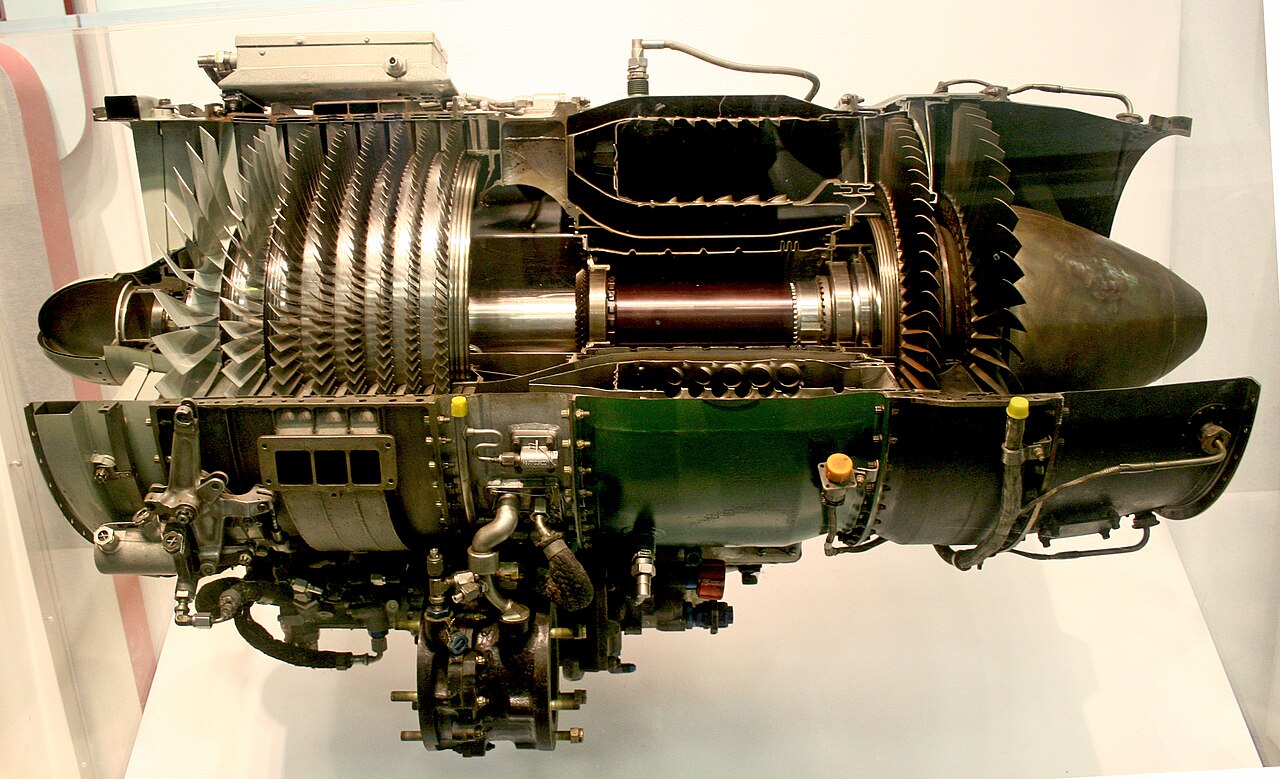
Photo: Sanjay Acharya / CC BY-SA 3.0 · via Wikimedia Commons
GE Aerospace Beats Again. Why the Stock Won't Follow
Another Beat-and-Raise, Led by Commercial Engines
GE Aerospace reported third-quarter 2026 results on Oct. 20 that beat expectations across the board. Adjusted earnings per share were $2.25, up 36% from $1.66 a year earlier and well above consensus around $2.00 to $2.01. Adjusted revenue was $13.29 billion, up 18% year over year and ahead of estimates near $12.85 billion to $12.88 billion. On a GAAP basis, revenue was $14.12 billion, up 16%.
Orders Jump 49% as Demand Stays Solid
Total orders reached $19.0 billion, up 49%, which management described as evidence of solid demand. Profit from continuing operations was $2.41 billion, or $2.32 per share, compared with $2.17 billion, or $2.04 per share, a year earlier. GAAP profit was about $2.8 billion, up 12%. Operating profit rose 30% to $3.0 billion, with operating margin at 22.5%, up 220 basis points.
Commercial Services Does the Heavy Lifting Again
Commercial Engines & Services revenue rose 21% to $10.3 billion, with operating profit up 21% to $2.9 billion. Services revenue grew 17% and services orders rose 23%. The company said it was the sixth straight period with at least 20% growth in commercial engines and services revenue. Defense and Propulsion Technologies grew more slowly, with sales up about 6.7% to 7% and orders up 18%.
Guidance Raised Across the Board for the Fourth Time
GE Aerospace lifted full-year 2026 guidance on every metric. Adjusted EPS guidance moved to $8.00 to $8.10, up from $7.65 to $7.85 and above consensus near $7.92 to $7.94. Adjusted revenue growth is now seen at 19% to 20%, up from high-teens growth. Operating profit guidance rose to $10.9 billion to $11.0 billion from $10.55 billion to $10.75 billion, and free cash flow guidance rose to $9.1 billion to $9.4 billion from $8.9 billion to $9.2 billion. CEO Larry Culp said 2027 commercial services should grow low-double-digits, supported by a commercial services backlog of over $170 billion.
A Muted Market Reaction Exposes High Expectations
The market response was restrained. Investing.com noted shares fell 4.27% in premarket trading to $297.99 from a prior close of $311.28, leaving the stock about 23% below its 52-week high of $388.84. A Dow Jones report captured an early 0.6% rise to $313.23, underscoring choppy sentiment. The message is familiar: the beat was already priced in after a strong run, while investors focused on valuation, softer quarterly cash flow, and the pace of future growth. Jefferies reiterated its view after the beat, noting revenue came in 3% above expectations and profit 8% ahead.
What Comes Next Is Execution, Not Just Beats
For airlines and suppliers, record orders and backlog point to sustained aftermarket demand. For shareholders, the question is what finally lifts the stock: steady delivery on low-20s commercial growth this year, defense acceleration, and conversion of backlog into 2027 services growth. Quarterly free cash flow was $2.0 billion, down 14%, with operating cash flow at $2.2 billion, also down 14%. Until cash and deliveries reaccelerate, another beat-and-raise may not be enough.
Sources
- Investing.com
- Morningstar
- Quartz
- LSE.co.uk
- WTOP